

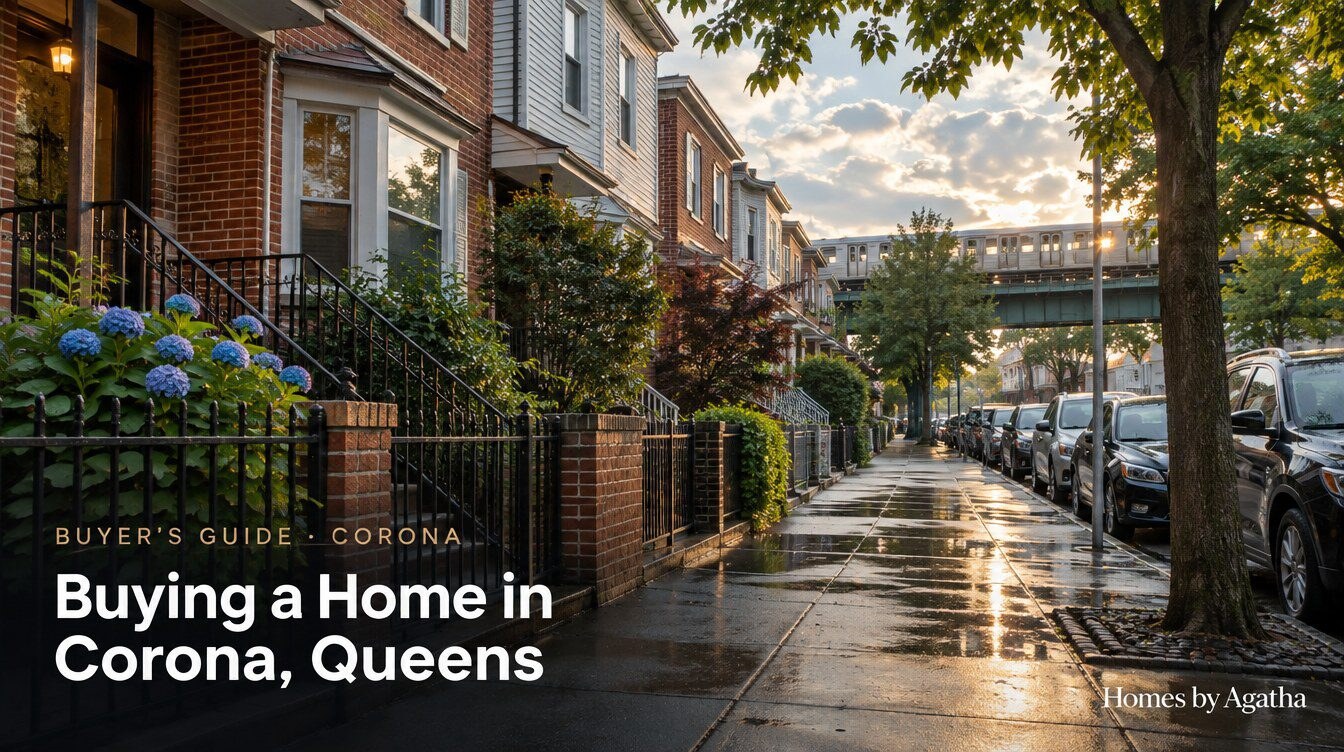
CORONA REAL ESTATE GUIDE
Buying a Home in Corona Queens: Legal Units, the 7 Train and the Paperwork That Protects You
Quick Answer
Buying a home in Corona, Queens usually means choosing among attached one-to-three-family houses, mixed-use buildings and a smaller supply of apartments. Before you make an offer, confirm the legal unit count on the Certificate of Occupancy, get pre-approved with a lender who understands rental income, budget for NYC closing costs, and map your walk to the 7 train.
This guide is for buyers who are seriously considering buying a home in Corona Queens and want to understand what they are actually purchasing before they fall for a listing. Corona sits between Jackson Heights, Elmhurst, East Elmhurst and Flushing Meadows Corona Park, and much of its housing is small residential buildings rather than large apartment complexes. That one fact changes the whole buying process.
When the property is a two-family or three-family house, the questions multiply. How many units are legal? Does the basement count? Can the rent from the second apartment help you qualify for a mortgage? Who pays the water bill? What happens to the tenant who already lives there?
As a Licensed Associate Real Estate Broker serving Queens, I help buyers evaluate both the property and the transaction, in English or Polish, whichever is more comfortable. Below you will find how Corona’s housing stock is organized, how to check a building’s legal status with the NYC Department of Buildings, how closing costs work for a New York City purchase, how the 7 train and the park affect day-to-day life, and a step-by-step checklist you can use from pre-approval to closing. When you are ready to see homes, the companion page on how to buy your home in Corona with a local buyer’s agent explains how we work together.
Corona at a glance
| Topic | What to know |
|---|---|
| Area | North-central Queens, west of Flushing Meadows Corona Park; bordered by Jackson Heights, East Elmhurst, Elmhurst and the Lefrak City / Rego Park area (neighborhood edges are informal) |
| Borough / County | Queens (Queens County), New York City |
| ZIP code(s) | 11368 covers most of Corona; some edge blocks may use neighboring ZIP codes, so confirm the ZIP code with USPS and the community district on NYC Planning’s maps for each specific address |
| Subway | 7 train at Junction Blvd (local and express stop), 103 St–Corona Plaza and 111 St (local stops); Mets–Willets Point lies just east, by the park |
| Rail | Long Island Rail Road Port Washington Branch at Mets–Willets Point, served full-time since April 2023, though some peak-hour trains skip the stop |
| Buses | Local buses serve Corona’s main streets; check the current MTA Queens bus map for routes and stops, since the Queens bus network was redesigned |
| Parks and landmarks | Flushing Meadows Corona Park (Unisphere, Queens Museum, Queens Zoo), New York Hall of Science at 47-01 111th Street, Louis Armstrong House Museum at 34-56 107th Street, Corona Plaza, Citi Field and the USTA Billie Jean King National Tennis Center nearby |
| Commercial corridors | Roosevelt Avenue, Junction Boulevard, National Street, 108th Street, Corona Avenue, Northern Boulevard on the northern edge |
| Typical property types | Attached and semi-attached one-to-three-family houses, row houses, some detached frame houses, mixed-use buildings with storefronts, walk-up apartment buildings, a limited number of condo and co-op units |
| Key buyer considerations | Legal unit count and Certificate of Occupancy, basement vs. cellar use, older building systems, existing tenants, proximity to the elevated 7 train, event-day traffic near the park |
What kind of homes will you find when buying a home in Corona Queens?
Most homes for sale in Corona, Queens are small residential buildings: attached or semi-attached houses with one, two or three apartments, plus mixed-use buildings on the commercial streets. Condo and co-op apartments exist but make up a smaller share of what buyers typically see here than in neighborhoods built around apartment towers.
That mix matters because each property type is bought, financed and inspected differently. A buyer who walks into Corona expecting a condo-style process, where a managing agent and a building budget answer most questions, will find instead that the buyer and the buyer’s attorney must investigate the building itself.
Attached and semi-attached houses
Many Corona blocks are lined with houses that share one or both side walls with their neighbors. Attached houses use land efficiently, which is why they are common in neighborhoods that grew up near subway and elevated-train lines. For a buyer, a shared wall means three practical things: the roof and parapet may connect to the neighbor’s, water problems can travel between houses, and any exterior work on a party wall may require coordination with the adjoining owner.
Semi-attached houses share one wall and often have a side driveway or walkway on the other side. That side strip can matter a lot in Corona, where on-street parking near Roosevelt Avenue and Junction Boulevard is in demand. Whether a driveway is legal, shared, or just a walkway that people park on is a question for the survey and the deed, not the listing photos.
Two-family and three-family houses
A two-family house is a building legally approved for two separate dwelling units, each with its own kitchen and bathroom. A three-family house is approved for three. In Corona, these properties are popular with buyers who want to live in one unit and rent another, and with investors who rent all of them.
The legal unit count is the single most important fact about a multi-unit house. It decides how the property is taxed, how a lender underwrites it, which closing-tax rates apply, and whether the rental income you are counting on can legally exist. For a broader explanation of owner-occupied rentals across the borough, see our guide to buying a multi-family home in Queens; the sections below focus on how to verify the count for a Corona property.
Mixed-use buildings on the commercial streets
A mixed-use building combines a commercial space, typically a ground-floor store, with apartments above. In Corona these appear mainly along Roosevelt Avenue under the elevated 7 train, on Junction Boulevard, on National Street and along parts of 108th Street and Corona Avenue. Mixed-use buildings can be financed with residential mortgages only in certain configurations; many require commercial lending, larger down payments and an income-focused appraisal.
Condos and co-ops
A condominium (condo) unit is real property: you receive a deed and pay monthly common charges plus your own property taxes. A cooperative (co-op) apartment is different: you buy shares in a corporation that owns the building and receive a proprietary lease, and your monthly maintenance usually includes a share of the building’s property taxes and any underlying mortgage. Co-op purchases require a board application and usually an interview, and each building sets its own financing and down-payment rules, so ask the managing agent for the current requirements before you make an offer.
Because Corona’s apartment inventory is limited, buyers who want a co-op or condo often compare listings across neighborhood lines. Nearby options include buying a home in Rego Park, where apartment buildings are more common, and the co-op stock in Jackson Heights.
| Property type in Corona | What you own | Monthly costs beyond the mortgage | Key diligence item | Typical financing path |
|---|---|---|---|---|
| One-family house | Land and building (deed) | Property tax, insurance, water/sewer, all repairs | CO or Letter of No Objection matches one unit; no unpermitted extra apartment | Standard residential mortgage |
| Two- or three-family house | Land and building (deed) | Property tax, insurance, water/sewer for the building, repairs for every unit | Legal unit count, existing leases, separate utilities | Residential mortgage for 1–4 units; rental income may be partly counted |
| Mixed-use building | Land and building (deed) | Commercial insurance, tax, repairs, possible vacancy | CO for both commercial and residential use; commercial lease terms | Often commercial lending; varies by configuration |
| Condo unit | Unit plus share of common elements (deed) | Common charges plus separately billed property tax | Offering plan, budget, reserves, pending assessments | Residential mortgage; building must meet lender requirements |
| Co-op apartment | Shares and a proprietary lease | Maintenance (usually includes building tax and underlying mortgage share) | Board rules, financials, sublet and financing policies | Share loan; board sets minimum down payment |
Not sure which Corona property type fits your plan?
Tell me how you want to live and how you plan to pay, and I will help you narrow the search to the building types that actually match.
How do you confirm how many legal units a Corona house has?
You confirm the legal unit count by checking the building’s Certificate of Occupancy (CO) in NYC Department of Buildings records, or, for many older buildings, its Letter of No Objection or other DOB records, and then comparing that document with what physically exists inside the house. The listing description is not proof. Neither is a seller’s statement that “it has always been a two-family.”
What a Certificate of Occupancy tells you
A Certificate of Occupancy is the NYC Department of Buildings document that states a building’s legal use and occupancy, including how many dwelling units it may contain and what each floor may be used for. If the CO says two families and you see three kitchens, at least one apartment is not legal.
CO records can be searched online through the DOB’s public systems (the Buildings Information System, known as BIS, and DOB NOW). Your attorney or title company will also review the building’s legal status as part of the contract and title process, but it is far better to look before you negotiate a price that assumes income from an extra unit.
Older buildings and the Letter of No Objection
Many Corona houses predate 1938, and the NYC Department of Buildings generally did not require Certificates of Occupancy for buildings constructed before January 1, 1938, unless the building was later altered in a way that changed its use, exits or occupancy. For those buildings, a buyer may find no CO at all. That is not automatically a problem.
In that situation, the DOB can issue a Letter of No Objection (LNO), a document confirming that the existing use is acceptable to the Department when the building’s use complies with code and zoning and its occupancy and exits are unchanged. The DOB explains this process on its Certificate of Occupancy page. If neither a CO nor an LNO exists, your attorney will look at other records, such as historical building cards and the tax classification, to understand what the building legally is.
Basement vs. cellar: why the difference matters in Corona
Under New York City building rules, a basement is a story that is partly below curb level but has at least half of its height above curb level, while a cellar has more than half of its height below curb level. A cellar generally cannot be legally used as a separate apartment. A basement may be habitable only if it meets strict requirements for ceiling height, light, ventilation and exits.
This is not a technicality. The remnants of Hurricane Ida in September 2021 flooded basement and cellar units across Queens, and the city has since treated below-grade housing as a serious building-code and flood-risk issue. New York State and New York City have created a pilot program to legalize certain existing basement and cellar apartments in one- and two-family homes, but it is limited to specific community districts named in Local Law 126 of 2024, excludes flood-prone areas, and requires an application and a multi-year path to full code compliance. An existing unpermitted unit is not legal simply because such a program exists, so check the current eligibility rules on the NYC Department of Buildings and HPD websites for any specific address.
For a buyer, an illegal below-grade unit creates four risks: the lender will not count its rent, insurance may not cover it, the city can issue violations requiring it to be vacated, and you inherit the liability the day you close.
Cross-checking the records
The CO is the starting point, not the only check. A careful Corona buyer cross-references several public records before signing a contract.
| Record | Where to find it | What it shows | Red flag for a buyer |
|---|---|---|---|
| Certificate of Occupancy / Letter of No Objection | NYC Department of Buildings (BIS, DOB NOW, borough office) | Legal use and number of units | More kitchens, doors or meters than legal units |
| DOB complaints, violations and permits | NYC Department of Buildings online records | Open violations, work done with or without permits, open job filings | Open “work without a permit” violations or permits never signed off |
| OATH / ECB violations | NYC Office of Administrative Trials and Hearings records | Penalties tied to building or sanitation violations | Unpaid penalties that may need resolution before closing |
| Property tax class and assessment | NYC Department of Finance | Tax class (Class 1 covers most residential properties of up to three units) and building description | Building class that does not match the unit count being marketed |
| Deeds, mortgages and liens | ACRIS (NYC Department of Finance) | Ownership chain, recorded mortgages, easements, some liens | Unreleased mortgages, recorded agreements affecting a shared driveway |
| HPD registration and violations | NYC Department of Housing Preservation and Development | Registration of rental buildings and housing-maintenance violations | Open HPD violations in a tenant-occupied building; missing annual registration, which HPD requires for buildings with three or more units and for one- and two-family homes where neither the owner nor the owner’s immediate family lives |
Key Takeaways
- The legal unit count on the CO or Letter of No Objection, not the listing, defines what a Corona house is.
- Pre-1938 buildings may lawfully have no CO; ask what other DOB records establish their use.
- A cellar generally cannot be a legal apartment, and an unpermitted basement unit is a liability, not income.
- Cross-check DOB, OATH, Department of Finance, ACRIS and HPD records before you sign a contract.
Can rental income from a Corona two-family house help you qualify for a mortgage?
Yes, rental income from a legal second or third unit can often be used to help you qualify, but lenders count only documented rent from legal units, and usually only a portion of it. Rent from an illegal basement or attic apartment is not counted, and its presence can complicate the appraisal itself.
How lenders look at a one-to-four-family purchase
Residential mortgage programs treat buildings with one to four units as residential property. When you plan to live in one unit, government-backed and conventional programs may allow lower down payments than investor loans. The appraiser estimates market rent for the other units, and the lender applies its own rules to decide how much of that rent can offset your housing payment. Rental-income percentages and reserve requirements differ by program and change over time, so confirm the current rules with an NMLS-registered loan originator.
A pre-approval for a Corona multi-unit property should therefore say more than a dollar amount. Ask your loan originator three questions in writing: Does the approval assume rental income? How much? And what happens to the approval if the appraisal finds fewer legal units than the listing advertises?
Buying with tenants in place
Many Corona two-family and three-family houses are sold with tenants living in one or more units. Existing leases generally remain in effect after a sale, which means the new owner takes over the landlord’s obligations, including security deposits. Your contract should require the seller to deliver copies of every lease, a rent roll and an estoppel statement or similar confirmation of rent and deposit amounts.
If you need a unit vacant at closing so that you can move in, that must be negotiated and written into the contract, and the seller is responsible for lawfully delivering it. New York’s tenant protection laws limit how and when a tenancy can end, so your attorney, not a handshake, should decide whether a “vacant at closing” promise is realistic. The rules depend on the specific tenancy, including whether any unit is rent regulated, which NYS Homes and Community Renewal can confirm.
Pre-approval that fits Corona’s housing stock
Pre-approval is a lender’s conditional commitment based on your verified income, assets and credit. In Corona, where so many listings are multi-unit, a strong pre-approval names the property type you are targeting. A letter for a “one-family home” does not tell a seller that you can close on a three-family house with commercial space. If you are new to the process, our first-time home buyer guide for Queens walks through the paperwork lenders request.
Planning to live in one unit and rent another?
Before you shop, let’s review which Corona configurations your pre-approval actually covers, and which questions to bring back to your lender.
How much cash do you need when buying a home in Corona Queens?
You need the down payment, plus buyer closing costs that in New York City include the mortgage recording tax, title insurance, attorney fees and lender charges, plus reserves for the building itself. For multi-unit houses, add a realistic repair and vacancy cushion, because you are buying every unit’s roof, boiler and plumbing.
Taxes a Corona buyer may pay at closing
Corona is in New York City, so city and state transaction taxes both apply. Under the rates published by the NYC Department of Finance and New York State, the mortgage recording tax on one-to-three-family homes and condos is roughly 1.8% of the loan amount for loans under $500,000 and 1.925% for loans of $500,000 and above. Co-op loans are share loans and are not subject to mortgage recording tax. Buildings with four or more units and mixed-use buildings fall outside the one-to-three-family category and are taxed at different, generally higher, rates, so ask your attorney to calculate the figures for that kind of property.
The New York State “mansion tax” is 1% of the purchase price on residential purchases of $1 million or more and is paid by the buyer; within New York City, the rate is graduated above $2 million. The NYS real estate transfer tax and the NYC Real Property Transfer Tax are customarily paid by the seller, though contract terms can shift costs, so read the draft contract carefully. Confirm current rates with the NYS Department of Taxation and Finance and NYC Department of Finance before closing.
Upfront costs vs. ongoing costs
| Cost | Upfront or ongoing | How it applies to a Corona purchase |
|---|---|---|
| Contract deposit | Upfront, at contract signing | Commonly held in escrow by the seller’s attorney and credited at closing |
| Mortgage recording tax | Upfront | Based on the loan amount; not charged on co-op share loans |
| Mansion tax | Upfront | Only if the price is $1 million or more |
| Title insurance and title search | Upfront | Protects against title defects; the search also surfaces municipal violations |
| Buyer’s attorney | Upfront | Negotiates the contract and reviews title, CO and leases |
| Lender fees and appraisal | Upfront | Multi-unit appraisals may include a rent analysis |
| Escrow for taxes and insurance | Upfront and ongoing | Lenders often collect several months in advance |
| Property tax | Ongoing | Billed by NYC Department of Finance; Class 1 for most one-to-three-family homes |
| Water and sewer | Ongoing | Billed to the building by NYC DEP; owners of rental units often pay for all units |
| Insurance | Ongoing | Landlord coverage needed for rented units; flood coverage is separate |
| Maintenance reserve | Ongoing | Roof, boiler, plumbing and electrical for every unit |
For a line-by-line explanation of typical buyer and seller costs across the borough, read Queens closing costs explained. Your attorney and lender should give you a written estimate for your specific purchase before you sign the contract.
The hidden budget line: bringing a building up to its legal status
If due diligence shows an unpermitted unit or open violations, someone has to pay to correct them. Removing an illegal kitchen, filing to legalize work, or clearing violations can involve architects, expediters and contractors. Negotiate this before contract, either through a price adjustment, a seller repair obligation, or a decision to walk away. Assuming you will “deal with it later” is how buyers end up paying twice: once in the purchase price and again in the correction.
Key Takeaways
- Corona purchases carry New York City and New York State closing taxes; the buyer typically pays the mortgage recording tax and, at $1 million or more, the mansion tax.
- Co-op share loans are not subject to mortgage recording tax; four-family and mixed-use buildings can carry different rates.
- Budget for every unit’s systems, the building’s water bill and landlord insurance, not just the mortgage.
- Price any legalization or violation cleanup into the deal before signing.
How does the 7 train shape where you buy in Corona?
The 7 train is Corona’s main rail link to Manhattan, and how far a house sits from Junction Blvd, 103 St–Corona Plaza or 111 St affects daily commute time, street noise and how easily a unit rents. Junction Blvd is both a local and an express stop, while 103 St–Corona Plaza and 111 St are local-only, which matters during rush hours when express service runs.
Stations and what they mean for a buyer
All three Corona stations are elevated, running above Roosevelt Avenue. Elevated lines bring two trade-offs that buyers should judge in person: homes and apartments within a short walk save time, but buildings directly facing the structure hear and see the trains. Visit a property at rush hour, not only on a quiet weekend afternoon.
Because the 7 runs through Long Island City and on to Grand Central and Times Square, Corona works for commuters headed to Midtown and to Long Island City. Toward the east, the line continues to Mets–Willets Point and Flushing–Main Street. Express service from Junction Blvd skips local stops in western Queens, so a buyer near Junction Boulevard may experience a different commute than one near 111th Street. Check MTA schedules for the hours you actually travel.
The Long Island Rail Road option
The Long Island Rail Road’s Port Washington Branch stops at Mets–Willets Point, just east of Corona across the park edge. The MTA restored full-time, year-round service at that station in April 2023, giving some Corona residents a rail alternative toward Penn Station or Grand Central Madison and toward Nassau County. Some peak-hour trains do not stop at Mets–Willets Point, so check the current Port Washington Branch timetable for the hours you would travel. For buyers on the eastern side of Corona, near 111th Street, the walk to that station can be a reasonable option to compare.
Buses, highways and LaGuardia Airport
Local buses link Corona with the surrounding Queens neighborhoods, and LaGuardia Airport lies a short drive to the north. Because the MTA redesigned the Queens bus network, check current route numbers and stops on the MTA bus map rather than relying on older guides. Drivers use the Long Island Expressway, Grand Central Parkway and Van Wyck Expressway, which border or cross the park area, though access points vary by block.
Flushing Meadows Corona Park and event days
Flushing Meadows Corona Park, site of the 1939 and 1964 World’s Fairs, forms Corona’s eastern edge. It contains the Unisphere, the Queens Museum and the Queens Zoo, and the New York Hall of Science sits at 47-01 111th Street at the park’s edge. The park was created on land that had been the Corona Ash Dumps, a history worth knowing when you read about low-lying ground and stormwater near the park.
Citi Field and the USTA Billie Jean King National Tennis Center, home of the US Open, are next to the park. On game and tournament days, trains are fuller and some streets carry more traffic and parking pressure. Buyers near 111th Street and the park should visit on an event day to see whether the pattern matters to them.
Corona also has its own cultural landmarks. The Louis Armstrong House Museum, at 34-56 107th Street, preserves the house where the musician lived from 1943 until his death in 1971; it is a National Historic Landmark and a New York City Landmark. Corona Plaza, the public plaza by the 103 St station, and William F. Moore Park at 108th Street and Corona Avenue are everyday gathering spaces on the commercial streets.
Building a Corona shortlist block by block?
We can compare specific streets by walk time to the 7, distance from the elevated tracks and event-day traffic before you commit to a showing schedule.
What should a home inspection focus on in an older Corona house?
A Corona home inspection should focus on the systems that serve more than one household (roof, heating plant, electrical service, plumbing and drainage) and on any work that looks newer than the permits on file. In a multi-unit building, a single failed system affects every tenant and every rent check.
Roofs, facades and shared walls
Attached houses frequently have flat or low-slope roofs connected to the neighbors’ roofs. Ask the inspector to check the roof surface, flashing at the party walls, parapets and drains. Exterior siding added over original materials can hide water damage; the inspector should look for staining and soft spots inside, especially around windows on the top floor.
Heating, oil tanks and fuel conversions
Many older Queens houses were originally heated with oil, and some later converted to gas. If a building converted, ask whether the old oil tank was removed or properly abandoned, and whether paperwork exists. A buried tank that was never addressed can become an environmental cost. Your attorney can request tank documentation, and a tank sweep is a separate inspection worth discussing.
Electrical service and separate meters
A legal two-family or three-family house usually has separate electric meters for each unit. Count the meters and compare them with the legal unit count. Older service capacity may be too small for modern appliances, air conditioners and the needs of several households, and upgrading service requires licensed electricians and utility coordination.
Plumbing, sewer lines and backwater valves
Older cast-iron and galvanized piping, sewer laterals running to the street, and the absence of a backwater valve are common inspection topics in Queens houses with below-grade space. A sewer camera inspection can show root intrusion, breaks or sags in the line between the house and the city sewer. Because the property owner is generally responsible for the house’s sewer connection, this inspection can prevent an expensive surprise.
Flood and stormwater exposure
Corona is an inland neighborhood, not a coastal one, but inland flooding during heavy rain is a real risk in parts of Queens. Check the FEMA Flood Insurance Rate Map for the address, and also the NYC Stormwater Flood Maps, which model flooding from intense rainfall rather than storm surge. Federally regulated lenders generally require flood insurance for properties in a Special Flood Hazard Area; outside it, coverage is optional but available. Check both maps for the specific address; do not assume any Corona block is in or out of a flood zone.
Lead paint in pre-1978 homes
Federal law requires sellers of homes built before 1978 to disclose known lead-based paint hazards and give buyers an opportunity to conduct a lead inspection or risk assessment. Since much of Corona’s housing is older, expect this disclosure in most transactions, and decide with your inspector whether a lead test makes sense, particularly if you plan to renovate.
Key Takeaways
- Inspect shared systems first; in a multi-unit house, one boiler or roof failure affects every unit.
- Ask for oil-tank removal or abandonment documentation when a house converted to gas.
- Match electric meters and kitchens to the legal unit count.
- Check both FEMA maps and NYC Stormwater Flood Maps; inland flooding is a separate risk from coastal flood zones.
How do offers and contracts work when you buy in New York?
In New York, an accepted offer is not a binding contract. After a seller accepts your offer, the buyer’s and seller’s attorneys negotiate and prepare the contract of sale, and the deal becomes binding only when both parties sign it and the deposit is delivered. That gap is your window for due diligence.
Why New York buyers inspect before signing
New York is an attorney state for residential sales: attorneys, not brokers, draft and negotiate the contract. Many New York City contracts give the buyer limited rights to cancel for physical condition once signed, so buyers usually complete the home inspection, review the CO and violation records, and read the leases before signing. In Corona, that means your attorney and inspector should both be ready to move quickly once your offer is accepted.
What a strong Corona offer includes
A strong offer is not only a high price. Sellers of multi-unit Corona houses compare the buyer’s financing type, down payment, proof of funds, flexibility on closing date, and willingness to take the building with tenants in place. If you need a vacant unit, say so up front. If your financing depends on rental income, make sure your lender has already reviewed the property type.
Contingencies to discuss with your attorney
A mortgage contingency lets you cancel if your loan is not approved within a set period, on the terms described in the contract. Other protections an attorney may negotiate include the seller’s obligation to deliver the building in a defined legal status, to cure specific violations before closing, to deliver specified units vacant, and to transfer tenant security deposits. Each is a negotiation point, not an automatic right.
How does working with a buyer’s agent work in Corona in 2026?
Under the rules in effect in 2026, following the 2024 NAR settlement, you sign a written buyer agreement with your agent before touring homes, and buyer-agent compensation is negotiable, not set by law and not automatically paid by the seller. Your agreement should state the compensation and how it will be paid.
At the first substantive contact, a New York real estate licensee must give you the NYS Disclosure Form for Buyer and Seller, which explains the possible agency relationships: buyer’s agent, seller’s agent, dual agency and other arrangements. Read it carefully; it tells you whose interests the licensee represents.
In some transactions, a seller agrees to contribute toward the buyer’s agent compensation or offers a closing credit; in others, the buyer pays under the buyer agreement. Either structure must be disclosed and agreed in writing. For a detailed explanation, see working with a buyer’s agent in NY.
In a neighborhood where so much depends on records and legal status, a buyer’s agent’s job includes pulling public building information before showings, flagging listings whose descriptions do not match DOB records, coordinating with your attorney and lender, and keeping the timeline moving. I work with buyers in English or Polish; that choice is about communication and comfort, and where you decide to buy is always your choice.
Ready to talk about an offer on a Corona house?
Before you write a number, let’s review the legal unit count, the leases and the contract protections your attorney may want to negotiate.
What is the step-by-step timeline from pre-approval to closing in Corona?
The purchase moves through six stages: pre-approval, search and records review, offer, attorney review and contract signing, mortgage and title work, and closing. In Corona, the stages most likely to slow down are records review and title work, because multi-unit and older buildings generate more documents and more questions.
| Stage | What happens | Who leads | Corona-specific delay risk |
|---|---|---|---|
| 1. Pre-approval | Lender reviews income, assets and credit; issues conditional approval | Buyer and loan originator | Approval not matched to two-family, three-family or mixed-use property |
| 2. Search and records review | Showings plus CO, DOB, OATH and Department of Finance checks | Buyer and buyer’s agent | Listings advertising more units than the CO allows |
| 3. Offer and acceptance | Price and terms agreed in principle; still not binding | Buyer’s agent and seller’s agent | Vacancy, tenant and closing-date terms left vague |
| 4. Inspection, attorney review and contract | Inspection, lease review, contract negotiation, deposit, signatures | Buyer’s attorney and inspector | Oil tank, sewer or violation findings reopening negotiations |
| 5. Mortgage commitment and title | Appraisal, underwriting, title search, municipal searches | Lender, title company, attorneys | Appraisal counting fewer legal units; open permits or violations in title report |
| 6. Closing | Final walkthrough, funds transfer, deed and mortgage recorded | Attorneys, lender, title closer | Lease transfers, deposit transfers and possession of vacant units |
Exact timing depends on the lender, the property’s records and both parties’ schedules. A cash purchase can move faster; a property with open violations or missing records can move slower no matter how motivated the parties are.
What mistakes do buyers make in Corona, and what should your checklist include?
The most common and most expensive mistake is paying for units that do not legally exist. The next most common are underestimating the cost of older building systems and treating an accepted offer as a done deal before the attorney has reviewed the building.
Mistakes to avoid
- Pricing rental income from an illegal unit. If the basement apartment is not on the CO, its rent should not be in your math or your lender’s.
- Skipping the rush-hour visit. Properties near Roosevelt Avenue feel different when the 7 is running every few minutes.
- Assuming “vacant at closing” without a contract clause. If you need a unit for yourself, the contract must say so and your attorney must assess whether it is achievable.
- Ignoring the park-side calendar. Event days near Citi Field and the tennis center change traffic and parking on nearby blocks.
- Relying on a generic pre-approval. A letter that does not address multi-unit property can weaken your offer.
- Forgetting the water bill and landlord insurance. These are owner costs in most rental arrangements.
- Not comparing neighboring areas. If Corona’s inventory does not fit, nearby homes in Elmhurst, Jackson Heights and Rego Park offer different mixes of houses and apartments.
Corona buyer checklist
- Get a written pre-approval that names the property type (one-family, two-family, three-family, mixed-use, condo or co-op).
- Sign a written buyer agreement and review the NYS Disclosure Form for Buyer and Seller.
- Set a budget that includes down payment, mortgage recording tax, title, attorney and lender fees, reserves, and repairs for every unit.
- For each serious listing, pull the CO or Letter of No Objection, DOB violations and permits, OATH records, tax class and ACRIS documents.
- Count kitchens, entrances and electric meters, and compare them with the legal unit count.
- Check FEMA and NYC Stormwater Flood Maps for the exact address.
- Visit at rush hour and, if near the park, on an event day.
- Request leases, rent roll, security-deposit details and utility information for tenant-occupied units.
- Hire an inspector and consider a sewer camera inspection and oil-tank sweep.
- Have your attorney review title, records and leases before you sign the contract.
- Confirm the mortgage commitment terms, including how rental income was treated.
- At the final walkthrough, confirm unit condition, vacancy terms and meter readings.
If you are also weighing a future sale of a home you already own, the companion guide on how to sell your home in Corona explains the seller side of the same transaction.
Want a second set of eyes on a Corona listing?
Send me the address you are considering, and we can review its public building records and due-diligence questions before you schedule an inspection.
Frequently asked questions about buying a home in Corona, Queens
What types of homes are most common in Corona, Queens?
Corona, Queens is dominated by attached and semi-attached one-to-three-family houses, row houses and mixed-use buildings with storefronts along Roosevelt Avenue, Junction Boulevard and National Street. Condo and co-op apartments exist but are a smaller share of listings, so many buyers compare nearby Rego Park or Jackson Heights for apartments.
How do I check if a Corona two-family house is legal?
Search the property in NYC Department of Buildings records for its Certificate of Occupancy or, for many pre-1938 buildings, a Letter of No Objection. Compare the legal unit count with the kitchens, entrances and electric meters you see. Your attorney should also review DOB violations, permits and the Department of Finance tax class.
Can a basement apartment in Corona be counted as a legal unit?
Only if NYC Department of Buildings records approve it as a dwelling unit. A cellar, more than half below curb level, generally cannot be a legal apartment. A basement unit must meet height, light, ventilation and exit rules. Lenders will not count rent from an unapproved below-grade unit, and it creates liability for the owner.
Which subway stations serve Corona, Queens?
The 7 train serves Corona at Junction Blvd, 103 St–Corona Plaza and 111 St, all elevated stations above Roosevelt Avenue. Junction Blvd is both a local and express stop, while 103 St–Corona Plaza and 111 St are local-only. Mets–Willets Point, just east by the park, also has Long Island Rail Road service.
What closing costs does a buyer pay in Corona?
Buyers in Corona typically pay the NYC mortgage recording tax on their loan, title insurance, attorney fees, lender fees and escrow deposits. The New York State mansion tax of 1% applies at $1 million or more. Co-op share loans are not subject to mortgage recording tax. Confirm current rates with NYC DOF and NYS DTF.
Can rental income from a Corona multi-family house help me get a mortgage?
Often yes, if the rented units are legal and the rent can be documented or supported by the appraisal. Lenders usually count only part of the expected rent and apply program-specific rules. Rent from an illegal unit is not counted. Ask your NMLS-registered loan originator how rental income affects your pre-approval before you shop.
Is Corona, Queens in a flood zone?
Corona is an inland Queens neighborhood rather than a coastal one, but flood exposure must be checked address by address. Review the FEMA Flood Insurance Rate Map and the NYC Stormwater Flood Maps, which model heavy-rain flooding. Lenders generally require flood insurance in Special Flood Hazard Areas; elsewhere, coverage is optional but available.
What happens to tenants when I buy an occupied house in Corona?
Existing leases generally continue after the sale, so the buyer becomes the landlord and takes over obligations such as security deposits. Your contract should require copies of leases, a rent roll and deposit details. If you need a unit vacant, negotiate it in writing and have your attorney confirm the plan complies with New York tenant law.
Do I need a buyer’s agent agreement before touring homes in Corona?
Yes. Under the rules in effect in 2026, buyers sign a written agreement with their agent before touring. The agreement states the agent’s compensation, which is negotiable, not set by law and not automatically paid by the seller. You should also receive the NYS Disclosure Form for Buyer and Seller at first substantive contact.
How does Flushing Meadows Corona Park affect buying near 111th Street?
Homes near 111th Street sit close to Flushing Meadows Corona Park, with the Queens Zoo, Unisphere and New York Hall of Science nearby. The same area sees heavier crowds and traffic on Citi Field and US Open event days. Visit on an event day and check stormwater maps for low-lying blocks near the park.
Your next step in Corona
Buying a home in Corona Queens rewards buyers who verify first and fall in love second. Confirm the legal unit count before you trust a rent estimate, align your pre-approval with the building type you are targeting, budget for New York City closing taxes and every unit’s systems, and test the commute and the park-side calendar in person. Once your criteria are clear, the page on how to buy your home in Corona, Queens with Agatha explains how we can search, review records and negotiate together.
Start your Corona search with a plan
A short conversation about your budget, property type and commute can save weeks of showings that never fit. English or Polish, whichever you prefer.
This article is for general informational purposes only and reflects conditions that may change. It is not legal, tax, or financial advice, an appraisal, or a guarantee of price or outcome; consult a licensed New York attorney, a CPA, and an NMLS-registered mortgage loan originator as appropriate. A CMA is an opinion of value, not an appraisal. Real estate brokerage services are offered by Agatha Lubas, Licensed Associate Real Estate Broker, NY License #10301213345, Keller Williams Realty Liberty, 96-10 101st Avenue, Ozone Park, NY 11416. The NYS Disclosure Form for Buyer and Seller, the NYS Housing and Anti-Discrimination Disclosure / Fair Housing Notice, and the brokerage’s Standard Operating Procedures are available on request. Equal Housing Opportunity.

Agatha Lubas helps buyers, sellers and investors across Queens, Brooklyn, Nassau County and Suffolk County understand both the property and the transaction before they commit. She works in English and Polish so clients can communicate in the language they find most comfortable.
Work with Agatha